A Singapore B2B software founder budgeted six months to close her Series A, the funding round meant to carry a company from early traction into real scale. She is eighteen months into the same raise now, and the number she checks every Monday morning is how many weeks of payroll are left, not last quarter’s revenue. That gap between the plan and the calendar is the whole of her week.
If your own round has run three times past the plan you pitched, you know the specific tired that comes from watching a number move by the week while the business only moves by the year. Rome had its own version of that arithmetic, at an empire’s scale.
Rome buried its dead by the cartload through the 160s and 170s, in a plague soldiers had carried home from the Parthian front. For fifteen years Marcus Aurelius governed an empire dying by the week while he held a war on the Danube at the same time. He kept a private practice for exactly that stretch, written down for no reader but himself.
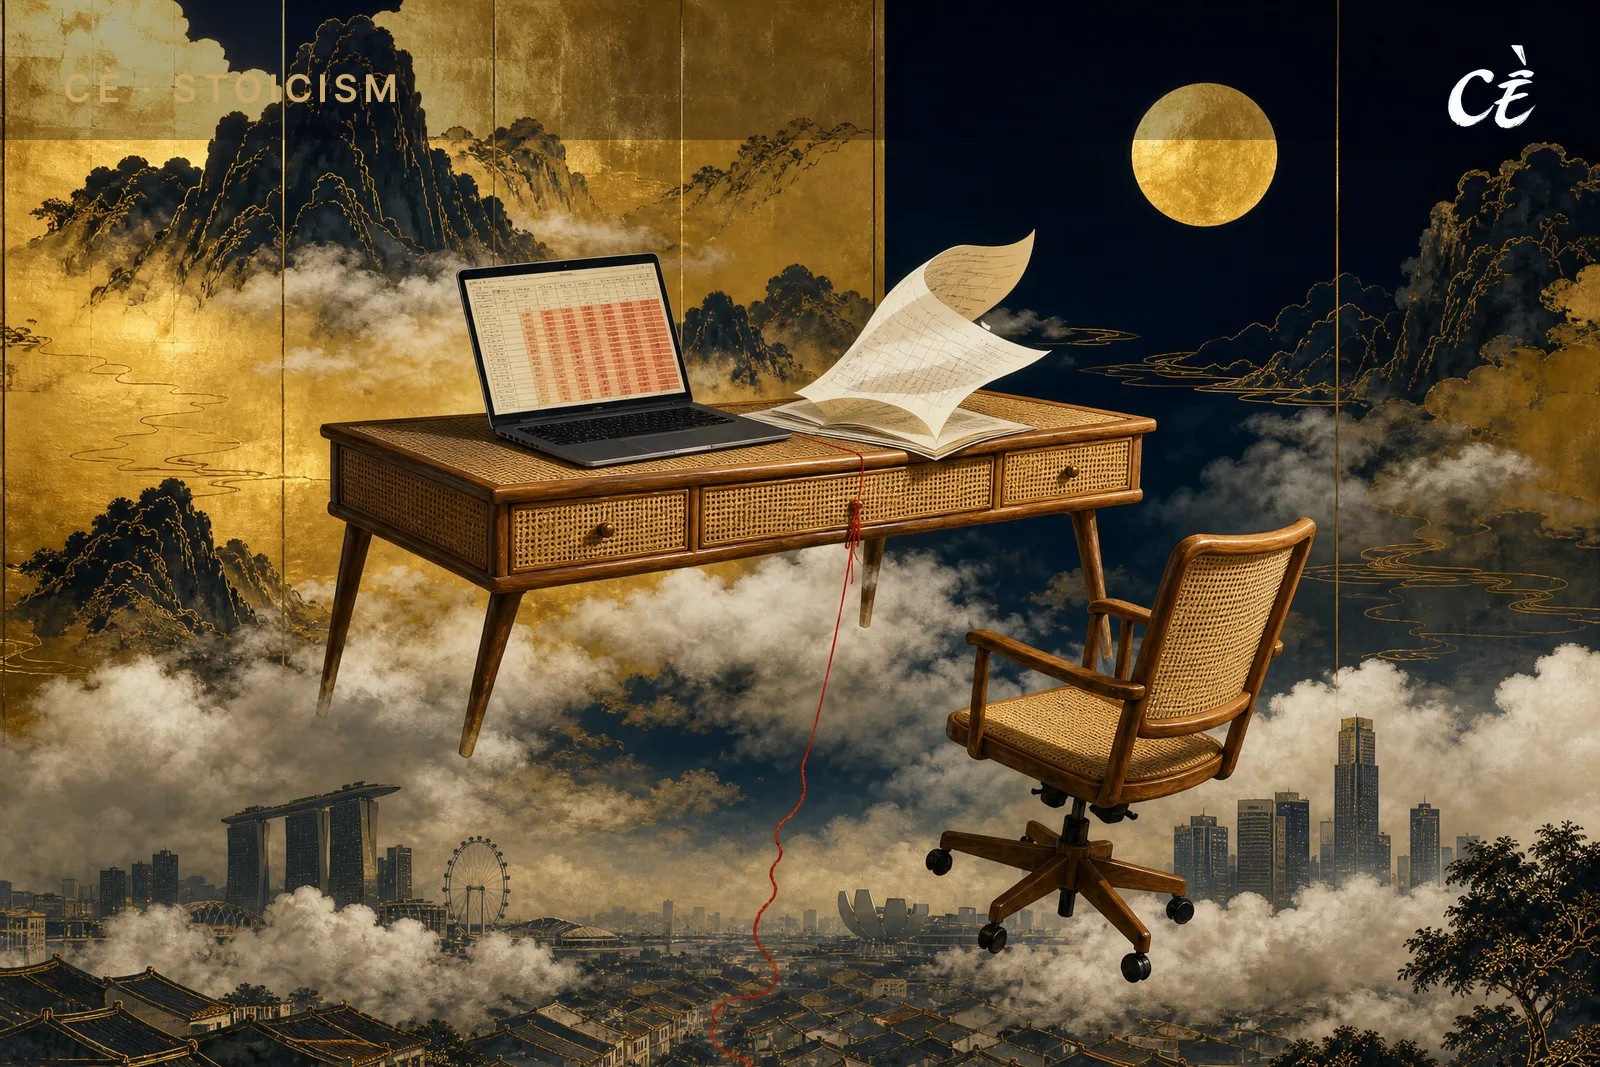
Climb, in the mind, above the camp, above the city, above the empire, until the funerals and the armies blur into one pattern too small to panic about.
Climb, in the mind, above the camp, above the city, above the empire, until the funerals and the armies blur into one pattern too small to panic about.
He called it the view from above. It was a tool for a man who could not afford to stop working.
He had no spreadsheet and no investor update due Friday. He had the same math problem you have this quarter. The founder in Singapore has no plague and no legions, only a laptop, a runway number, and eighteen months of the same Monday.
The market she is raising into changed underneath her: venture funding into Southeast Asian tech companies fell nearly 80 percent between 2022 and 2024, from about US$10.1 billion to about US$2.2 billion, and the correction never fully reversed.
By the first quarter of 2026 the region closed just 98 equity deals worth US$2.81 billion, the lowest quarterly deal count in at least eight years. The money still moving is moving to fewer companies in far bigger cheques. Startups raised US$12.8 billion in the first seven months of 2026, up 137 percent year on year, while the number of companies that closed a round fell 30 percent and the average round roughly tripled, to about US$72 million.
The reason sits one level above her deck: a whole region’s capital rotating toward fewer, later, larger bets, away from her size and stage entirely.
The practice only earns its name when it changes what she does next.
This is where the view from above earns its keep, and where it is easiest to misuse. The practice only earns its name when it changes what she does next. Used to explain away a bad market, it is just distance.
From the week, her eighteen months reads as failure: no signed offer, cash ticking down, a hundred calls that went nowhere. From three years out it reads differently: a company with eleven months of runway, raising into a year when the deals that close skew later-stage and larger than anything she is asking for.
The honest read from up there is that she has spent eighteen months chasing a shape of round the market is barely writing for companies her size this year.
So the decision she has been avoiding stops being whether to keep pitching, and starts being whether to ask her two largest investors for a bridge, a smaller top-up round built to buy time rather than prove a valuation. On sketched terms, it buys her fourteen more months. It is a smaller, less glamorous round, and it is the one the numbers say is on offer.
Marcus never made the plague end early by climbing above it. He came back down every time to the same tent, the same war, the same fifteen years that would not shorten just because he had finally seen them whole.
Her eighteen months were never going to shrink to six on their own. The decision underneath them was hers all along, and the climb is what let her finally see it.