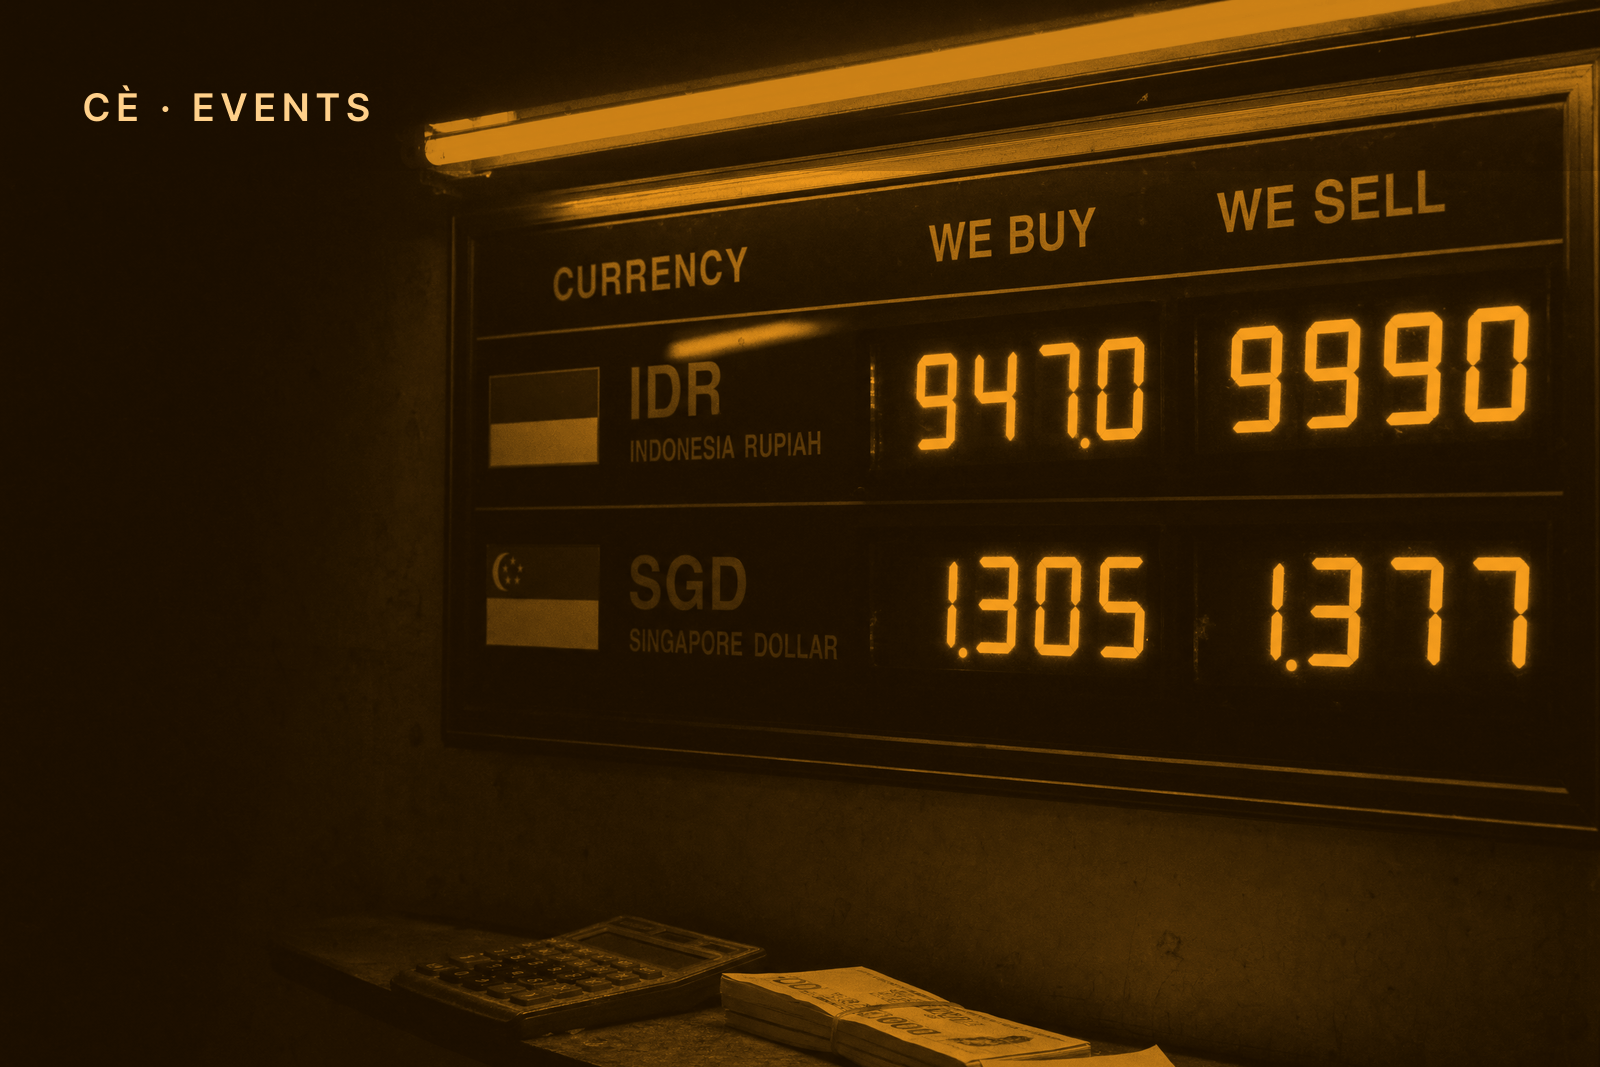
Bank Indonesia raised its policy rate to 5.75 percent on 18 June, which on its own is the kind of central-bank housekeeping that never makes it past the second screen of your news app (a quarter point, as the economists expected, in a year when half the world’s central banks are nudging rates around for one reason or another), except that nine days earlier the same bank had done something genuinely unusual. It called an unscheduled meeting on 9 June and hiked then too, the monetary-policy equivalent of pulling onto the hard shoulder because something under the bonnet could not wait for the next service.
The hike is currency defense, plainly stated. The economy is not running hot; the rupiah is under pressure from a firm dollar, and Bank Indonesia named the cause in its own statement: the war in the Middle East, the flight to dollars it set off, and the capital that always runs toward a strong dollar when something is on fire. So Jakarta is raising the price of money at home to stop money leaving, which is a thing you do when growth is the bill you are willing to pay.1
Jakarta is raising the price of money at home to stop money leaving, which is a thing you do when growth is the bill you are willing to pay.
For a Singapore operator with regional reach, a Bank Indonesia decision reads as somebody else’s domestic problem right up until you notice it is a pricing signal aimed at you. When the region’s largest economy is hiking to keep its currency from sliding, the soft-currency buyers across Southeast Asia are getting quietly poorer in Singapore-dollar terms, and your SGD-priced product just became more expensive to them without you touching the price. That is the unglamorous, durian-and-oysters version of macroeconomics: not a forecast, a margin.
And yet there is very little you can do about Bank Indonesia. Which is why the useful response is small and clerical. Somewhere in every business there is a list of who pays you and who you pay, and the only new column worth adding beside each name is the currency they actually transact in, with a mark against the ones weakening against the SGD. The sourcing line out of Malaysia looks better this quarter, because a firm SGD against a soft ringgit is a gift on the buy side (worth taking, not worth locking long). The premium bottle aimed at a buyer in Jakarta or Kuala Lumpur looks worse, because if their currency keeps drifting your price climbs every month while your invoice stays still. The domestic coworking floor, priced in SGD to SGD-earning tenants, is insulated, which is itself a useful thing to have confirmed.
The fortnight came and went, and the posture did not age.
Bank Indonesia held at 5.75 percent at its 18-19 August meeting. That leaves a full percentage point of hikes since May, with no cut in sight.2 The rupiah stood at 17,855 to the US dollar on 18 August, up 0.78 percent on the month: a currency held in place at a price.
Then the person holding it left. Governor Perry Warjiyo resigned on 27 July, two years before his second term was due to end, and Senior Deputy Governor Destry Damayanti took the chair as acting governor.3 Her first decision was continuity, and she gave the same reason the June statement did: the war in the Middle East and the volatility it keeps pumping through Asian currencies.
A central bank that loses its governor mid-defence and keeps defending is telling you how long it expects to be at this.
So the column stays. Check it once a month, on the day after Bank Indonesia’s decision, and ask one question of each buyer paid in rupiah or ringgit: has my price climbed for them since June?
It is just a column in a spreadsheet, which is the most any of us can usefully own of a war we are not fighting.
None of this is a call on the rupiah, which could firm the moment the oil stops burning and the dollar relaxes, at which point Bank Indonesia would go back to wanting to cut. It is just a column in a spreadsheet, which is the most any of us can usefully own of a war we are not fighting: the quiet knowledge of which of our prices were drifting while we were watching the rate.
Footnotes
-
Bank Indonesia would not say “stop money leaving”; it would say “rupiah exchange-rate stabilisation,” and it would be right to, because a central bank that announces it is defending the currency tends to find the market unusually keen to test how much it means it. ↩
-
Bank Indonesia held its deposit facility at 4.75 percent and its lending facility at 6.50 percent at the same meeting; July headline inflation was 2.88 percent, inside the 2.5 percent plus or minus one target. ↩
-
The resignation was announced by Minister of State Secretariat Prasetyo Hadi, who did not give a reason. ↩